
The building is finished. Tenants are moving in. And the investor calls about a cost segregation study for the first time.
It is not too late to benefit. It is simply not the ideal moment to start.
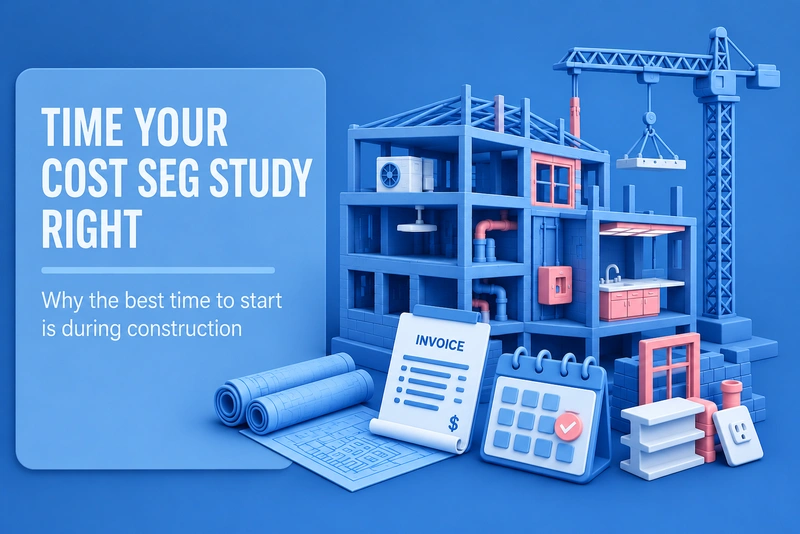
The strongest time to begin a cost segregation study is during construction. Every phase of building produces detailed documentation that a cost segregation engineer uses to identify and classify components. Once construction ends, that documentation is often consolidated, filed away, or lost, and the components become harder to substantiate.
This article explains the optimal timeline for commissioning a study on new construction. You will learn how the placed-in-service date works, why construction-phase documentation matters, and how timing affects your first-year deduction.
The Placed-in-Service Date: When Depreciation Begins
Depreciation does not begin when you break ground, pour the foundation, or frame the walls. It begins on the placed-in-service date. The IRS defines that as the date the property is ready and available for its specific use, per IRS Publication 946.
For rental property, that generally means the point when the space is ready and available to lease and is being held out to prospective tenants. A certificate of occupancy plus active marketing such as a listing, advertising, or engagement of a property manager, is the cleanest evidence. A certificate alone does not establish that the property is being offered for its intended use.
This date sets your depreciation start point, and it also controls your first-year bonus deduction.
The One Big Beautiful Bill Act (OBBBA) restored a permanent 100% bonus depreciation deduction for qualified property acquired and placed in service after January 19, 2025, per IRS guidance on the OBBBA. Qualified property includes assets with a recovery period of 20 years or less. That is exactly what a study reclassifies: 5-year, 7-year, and 15-year components. Those reclassified assets can be deducted in full in the placed-in-service year.
For self-constructed property, the acquisition date is generally when physical work of a significant nature begins; an optional 10% safe harbor can be used to establish that threshold. If significant physical work began before January 20, 2025, the project stays on the prior phase-down by placed-in-service year: 40% for 2025, 20% for 2026, and none after. If that work began after January 19, 2025, the permanent 100% rate can apply when the qualified property is placed in service. For a purchased building rather than a ground-up build, a written binding contract signed before January 20, 2025 can place the property on the prior schedule. Our Big Beautiful Bill breakdown covers the effective-date rules in detail.
Timing also controls which tax year the deduction lands in. For a calendar-year taxpayer, a building placed in service in November 2025 supports the deduction on the 2025 return. A building placed in service in January 2026 shifts that deduction to the 2026 return. A short construction delay can move the benefit by a full tax year.
For larger projects, partial placed-in-service treatment may apply. A multi-story building occupied floor by floor can begin depreciating completed floors while upper floors are still under construction. Each completed portion starts its own schedule.
Why Starting Your Study During Construction Matters
During construction, every dollar is documented. Contractor invoices list specific materials and labor. AIA pay applications break costs into detailed line items. Change orders describe exactly what was added or modified. This is the most detailed record your property will have.
After construction, those costs are often consolidated. The final invoice may show a single number. The closing statement lists a purchase price. The itemized trail fades into summary figures.
A cost segregation engineer working during construction can access:
- Draw schedules showing what was built and when
- Contractor invoices with line-item material and labor costs
- Change orders describing modifications with specific pricing
- Architectural and mechanical drawings showing system layouts
- Material specifications identifying product types and installation methods
Real-time access supports a more thorough and better-substantiated study. The engineer classifies components as they are installed rather than estimating costs after the fact. A later study might miss items like dedicated electrical circuits, specialized plumbing lines, and removable finishes. During construction, the engineer can capture and document them while they are visible.
Better documentation does not guarantee a specific reclassification percentage. It does make each classification easier to defend if the IRS reviews the study. That defensibility is the real value of engaging early.
Can I still do a cost segregation study if construction is already finished?
Yes. A study can be worthwhile at any point during ownership. If construction is complete, the engineer uses available records, site visits, and construction documents to classify components. If the property has been in service for prior tax years, Form 3115 lets you catch up on missed depreciation through a change in accounting method. The catch-up runs through a Section 481(a) adjustment, and IRS Form 3115 allows a favorable adjustment to be claimed without amending prior returns.
The Optimal Timeline: When to Engage a Cost Segregation Firm
There are four entry points for a study on new construction. Each one works. Earlier engagement gives the engineer more to work with.
Pre-construction. Engage the firm during design and budgeting. The engineer reviews plans and specifications before work begins and can flag choices that affect classification. For example, removable finishes such as carpet or vinyl plank are more readily classified as short-life personal property. Permanently affixed flooring usually stays with the building. Final classification always depends on how the component is installed and documented.
During construction. The firm reviews draw schedules, invoices, and change orders as they arrive. Classification happens in real time. The engineer can coordinate with the general contractor so invoices carry the detail a study needs.
At certificate of occupancy. The study begins as soon as the property is placed in service. Documentation is still current, and contractors remain available for questions. The study finishes before the first return is filed.
After the first tax year. The property has depreciated on the standard schedule. A study identifies the reclassifiable components, and Form 3115 captures the missed accelerated depreciation through a change in accounting method.
Earlier engagement gives you the richest records. Any timing beats never starting.
Construction Documentation That Strengthens Your Study
You know when to start. Here is what to have ready. The quality of your study depends on the quality of your documentation.
AIA pay applications (G702 and G703 forms). These break construction costs into detailed categories such as site work, concrete, masonry, metals, finishes, mechanical, electrical, and plumbing, with dollar amounts for each. An engineer maps these categories to IRS asset classifications.
Contractor invoices with line-item detail. Each invoice should list the work performed, materials used, and labor. Lump-sum invoices reduce what can be substantiated.
Change orders. Modifications often involve components that qualify for shorter recovery periods. Each change order should describe the specific work, materials, and cost.
Architectural and mechanical drawings. Floor plans, electrical layouts, and plumbing schematics help the engineer trace specialized systems.
Material specifications. Product data sheets confirm flooring types, cabinet materials, and fixture models, all of which affect classification.
Construction photography. Photos taken before walls are closed record installation methods. A virtual inspection relies on this kind of documentation.
More detail supports more defensible reclassification, and that protects your deduction.
What if I am the general contractor on my own project?
Owner-builders qualify for cost segregation studies just as third-party-built properties do. The methodology is asset-based, as the IRS Cost Segregation Audit Techniques Guide describes, so who managed the build does not change eligibility. Keep detailed records of every material purchase, subcontractor invoice, and labor allocation. The engineer needs the same level of detail regardless of who ran the project.
The Dollar Impact: How Documentation Affects Your Deduction
Here is an illustrative example. Treat the numbers as a hypothetical, not a promise. Actual results depend on property type, asset mix, and your tax profile.
Consider a $3 million commercial property with $600,000 in land value. Land is not depreciable, so the depreciable basis is $2.4 million. Land value is excluded before any reclassification.
Assume a study reclassifies 30% of the depreciable basis into shorter-life assets. That is $720,000. With 100% bonus depreciation, that $720,000 could be deducted in the first year. For an investor in the 37% marginal bracket, that is roughly $266,400 in first-year tax savings. The loss limits described below may reduce what you can actually use.
Without a study, the same $2.4 million depreciates over 39 years for nonresidential real property. Using the standard depreciation approach, that is about $61,538 per year, or roughly $22,769 in annual tax savings at 37%. A first-year reclassification of $720,000 delivers more than eleven years of those standard deductions at once.
One technical note: real property uses the mid-month convention, so the true first-year straight-line figure is slightly lower than the annual average shown here.
Why does construction-phase documentation matter to these numbers? It does not change the tax rate or the asset lives. It affects how much of the property the engineer can identify and substantiate. Complete records support a thorough study. Sparse records force more estimation and can leave defensible reclassification unclaimed.
Does a new-construction study cost more than a study on an existing property?
Pricing depends on property type, size, and complexity, not primarily on timing. Construction-phase studies are often more efficient because the documentation is organized and current, so the engineer spends less time reconstructing costs.
What to Confirm Before Counting the Savings
A large first-year deduction only helps if you can apply it. Three conditions decide that.
Passive activity loss rules. Rental real estate losses are generally passive. You usually cannot use them to offset wages or active business income. Exceptions apply if you qualify as a real estate professional or meet the short-term rental participation rules, which IRS Publication 925 explains. Review Real Estate Professional Status with your CPA before you rely on a first-year offset.
Depreciation recapture. Five- and 7-year personal property is Section 1245 property, and depreciation on those assets is generally recaptured as ordinary income when you sell. Fifteen-year land improvements are Section 1250 property: depreciation in excess of straight line, including bonus depreciation, is generally recaptured as ordinary income, while the remaining gain attributable to depreciation may be treated as unrecaptured Section 1250 gain, capped at 25%. The building's straight-line depreciation is also generally treated as unrecaptured Section 1250 gain, capped at 25%, as described in IRS Publication 544. Our guide to depreciation recapture explains how this affects your net benefit.
State conformity. Many states do not conform to federal bonus depreciation. Your state return may require you to add the accelerated amount back, so your combined benefit can differ from the federal figure.
One more planning note: interior improvements to nonresidential property may qualify as qualified improvement property. That property carries a 15-year recovery period and is eligible for bonus depreciation. Ask your engineer to flag it during the study.
Build Smart and Study Early
The construction phase gives a cost segregation study its strongest documentation. Records are current, costs are itemized, and each classification is easier to defend.
Key takeaways:
- Depreciation begins at the placed-in-service date, the date the property is ready and available for its intended use, not during construction.
- OBBBA restored permanent 100% bonus depreciation for qualified property acquired and placed in service after January 19, 2025. For self-constructed property, acquisition generally occurs when significant physical work begins; projects that began before January 20, 2025 follow the prior phase-down, 40% for 2025 placements, 20% for 2026, and none after. The binding-contract test generally applies to purchased buildings, not ground-up construction.
- Construction-phase records let the engineer identify and substantiate more short-life components, which protects your deduction if the IRS reviews the study.
- AIA pay applications, line-item invoices, and change orders are the documentation that supports the most defensible study.
- Form 3115 lets you catch up on missed depreciation in a single tax year without amending prior returns.
- A first-year deduction only helps if you can use it, so confirm passive loss limits, recapture, and state conformity with your CPA.
Timing can move tens of thousands of dollars between tax years and can affect how much you substantiate. Want to know what your build could support? Get a free proposal and see your estimated first-year savings.