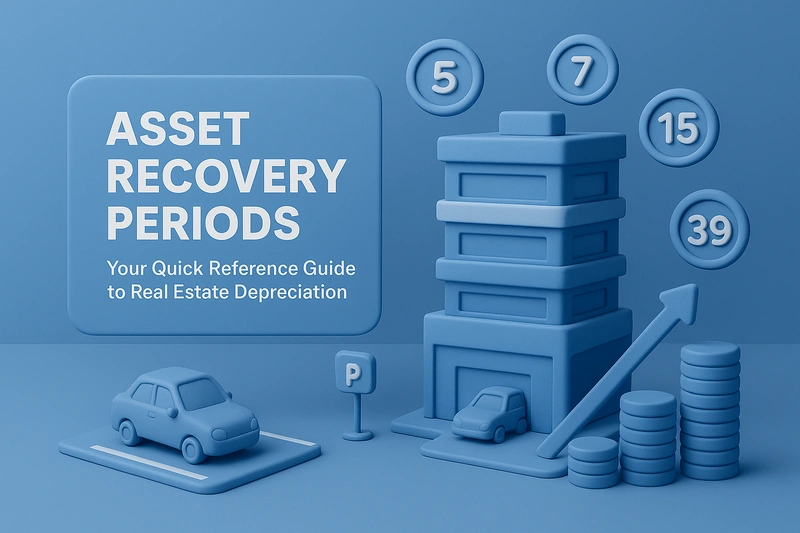

Asset recovery periods decide how quickly real estate investors can deduct each part of a property, and cost segregation is how those periods get assigned. With the Big Beautiful Bill now in effect, providing permanent 100% bonus depreciation for properties acquired and placed in service after January 19, 2025, asset classification matters more in year one.
The difference between classifying an asset as 5-year property versus 39-year property directly impacts your cash flow. A $100,000 parking lot improvement generates $5,000 in first-year depreciation as 15-year property (using 150% declining balance) compared to just $2,564 if incorrectly classified as 39-year property. With 100% bonus depreciation, that same parking lot generates an immediate $100,000 deduction when properly classified.
This guide simplifies complex IRS recovery periods into actionable categories real estate investors use daily. For investors working with R.E. Cost Seg, this serves as a companion resource to understand how professional cost segregation services identify and reclassify assets to accelerate depreciation.
What Is a Recovery Period in Depreciation?
A depreciation recovery period is the number of years the IRS assigns to an asset for tax depreciation. In real estate, recovery periods determine how quickly an investor can deduct the cost of each asset: personal property may use 5- or 7-year schedules, land improvements often use 15 years, residential rental buildings use 27.5 years, and commercial buildings use 39 years.
| Recovery period | Asset class | Common real estate examples | Why it matters |
|---|---|---|---|
| 5 years | Section 1245 personal property | Appliances, removable carpeting, decorative lighting, security systems, hotel furniture, specialized equipment | Often eligible for accelerated depreciation and bonus depreciation |
| 7 years | Office furniture and certain fixtures | Desks, chairs, conference tables, filing cabinets, modular workstations | Shorter recovery period than the building, but less common than 5-year property in cost segregation |
| 15 years | Land improvements and qualified improvement property | Parking lots, sidewalks, fencing, landscaping, irrigation, site lighting, certain interior nonresidential improvements | Can significantly accelerate deductions compared with 27.5- or 39-year building depreciation |
| 27.5 years | Residential rental real property | Apartment buildings, single-family rentals, duplexes, residential rental structures | Default recovery period for residential rental buildings and structural components |
| 39 years | Nonresidential real property | Office buildings, retail centers, warehouses, hotels, medical office buildings, commercial structural components | Default recovery period for commercial buildings and many structural systems |
Quick Reference: Common Recovery Periods
Quick Reference: Common Recovery Periods
| Asset Category | Recovery Period | Common Examples |
|---|---|---|
| Personal Property (§1245) | 5 Years |
• Computers, servers, and IT equipment • Kitchen equipment and appliances • Point-of-sale systems • Specialized process equipment • Removable carpeting • Window air conditioning units • Security systems • Data handling equipment • Decorative millwork and fixtures • Movable partitions • Window treatments • Display cases and shelving • Communication equipment • Decorative lighting fixtures • Hotel furniture and furnishings |
| Personal Property (§1245) | 7 Years | • Office furniture and workstations |
| Land Improvements (§1250) | 15 Years |
• Parking lots and driveways • Sidewalks and walkways • Fencing and gates • Landscaping and irrigation • Site lighting • Retaining walls • Storm drainage systems • Freestanding signage |
| Qualified Improvement Property | 15 Years |
• Interior improvements to nonresidential buildings • Non-structural interior walls • Ceiling systems • Interior doors • Mechanical/electrical/plumbing for interiors (Excludes enlargements, elevators, escalators) |
| Residential Rental (§1250) | 27.5 Years |
• Apartment buildings • Single-family rentals • Duplexes and multi-family homes • Student housing • Senior living (non-medical) • Manufactured home communities (Must meet 80% residential income test) |
| Nonresidential Real Property (§1250) | 39 Years |
• Office buildings • Retail centers • Warehouses • Hotels and hospitality • Manufacturing facilities • Medical office buildings • Building structural components • Central HVAC/plumbing/electrical |
Note: These classifications assume General Depreciation System (GDS) treatment. 100% bonus depreciation applies to assets with recovery periods of 20 years or less for properties acquired and placed in service after January 19, 2025.
5-Year Property: Technology, Equipment & Fixtures
Five-year property represents the shortest standard recovery period and encompasses a broader range than many investors realize. This category generates the most immediate tax benefits, especially with 100% bonus depreciation now permanent.
Technology & Equipment:
- Computers, servers, telecommunications systems
- Point-of-sale systems and cash registers
- Security systems beyond basic building requirements
- Kitchen equipment (ovens, fryers, refrigeration units)
- Medical equipment and specialized systems
- Appliances in rental properties (when removable)
Fixtures & Decorative Elements:
- Decorative millwork (crown molding, chair rails)
- Window treatments (blinds, curtains)
- Movable partitions not extending floor to ceiling
- Display cases and specialized shelving
- Decorative lighting fixtures
- All hotel furniture and furnishings
Key Test: Does the asset serve specific equipment/operations rather than the building generally? Is it removable without structural damage?
7-Year Property: Office Furniture
Seven-year property is surprisingly limited, consisting primarily of:
- Traditional office furniture (desks, chairs, conference tables)
- Filing cabinets and storage systems
- Modular workstation systems
This narrow category specifically excludes decorative fixtures, partitions, and specialty items that qualify for more favorable 5-year treatment.
15-Year Property: Land Improvements
Fifteen-year property includes all improvements to the land that aren't part of the building structure. These assets use 150% declining balance depreciation, providing accelerated deductions even without bonus depreciation.
Site Infrastructure:
- Parking lots, driveways, and loading areas
- Sidewalks and walkways
- Retaining walls and drainage systems
- Site utilities (when not serving the building)
Landscaping & Amenities:
- Trees, shrubs, sod, and plantings
- Irrigation systems
- Fencing and gates
- Security bollards and barriers
Signage & Lighting:
- Freestanding signs and monuments
- Parking lot lighting
- Perimeter security lighting
Qualified Improvement Property (15-Year)
QIP includes interior improvements to nonresidential buildings placed in service after the building's initial service date:
- Interior build-outs
- Non-structural walls and partitions
- Ceiling and flooring systems
- HVAC modifications for specific spaces
Excludes: Building enlargements, elevators, escalators, and structural framework
27.5-Year Residential Rental Property
Residential rental property qualifies for 27.5-year straight-line depreciation when at least 80% of gross rental income comes from dwelling units:
- Apartment complexes
- Single-family rentals
- Student housing (non-transient)
- Senior living facilities (non-medical)
The 80% test excludes income from services, separately charged parking, and laundry facilities. Properties failing this test depreciate over 39 years.
39-Year Nonresidential Real Property
Commercial buildings and their structural components depreciate over 39 years:
- Office buildings and retail centers
- Hotels and hospitality properties
- Warehouses and industrial facilities
- Building shell and structural systems
- Central HVAC, plumbing, and electrical serving the building
Key Distinction: Systems serving the building generally (39-year) versus systems serving specific equipment or limited areas (5-year).
Practical Application Examples
Medical Office Building:
- Building structure: 39 years
- Central HVAC: 39 years
- Medical equipment: 5 years
- Oxygen/gas outlets for equipment: 5 years
- Office furniture: 7 years
- Parking lot: 15 years
Hotel Property:
- Building structure: 39 years
- Guest room furniture: 5 years
- Lobby furnishings: 5 years
- Decorative fixtures: 5 years
- Landscaping: 15 years
Retail Center:
- Building shell: 39 years
- Display fixtures: 5 years
- Checkout counters: 5 years
- Parking lot and sidewalks: 15 years
- Monument signage: 15 years
Common Classification Errors to Avoid
- Classifying all furniture as 7-year property - Hotel furniture, decorative fixtures, and movable partitions are 5-year property
- Missing 15-year land improvements - Parking lots, landscaping, and site lighting often get incorrectly included with the building
- Overlooking specialized systems - Equipment-specific electrical, plumbing, and HVAC qualify for 5-year treatment
- Defaulting everything to 39 years - Qualifying costs may belong on shorter recovery periods. The share depends on the asset class: office 28–41%, industrial/warehouse 25–39% and medical office 27–42% of depreciable basis, rather than one blended percentage.
Key Takeaways
With permanent 100% bonus depreciation for qualifying property acquired and placed in service after January 19, 2025, asset classification matters more in year one. There is no single commercial-property allocation. For example, the office-building baseline allocates depreciable basis as follows:
- 16% in 5-year property
- 0% in 7-year property in this benchmark
- 12% in 15-year land improvements
- 72% remaining in 39-year building property
That totals 100% of depreciable basis, with 28% reclassified. The office optimal case is 22% five-year, 0% seven-year, 19% fifteen-year and 59% building property, for 41% total reclassification. Use the paired baseline or optimal allocations rather than mixing component endpoints. Land is excluded before calculating any of these percentages. Other classes differ: industrial/warehouse 25–39%, medical office 27–42% and apartment building 26–38%. See our reclassification percentages by property type. These are planning benchmarks, not a substitute for an engineering-based study; separately purchased equipment is depreciated outside the building percentage.
Professional cost segregation studies document these classifications with engineering-based analysis, supporting each classification if the IRS asks. For properties over $500,000, the first-year tax savings typically exceed the study cost 10 times over.