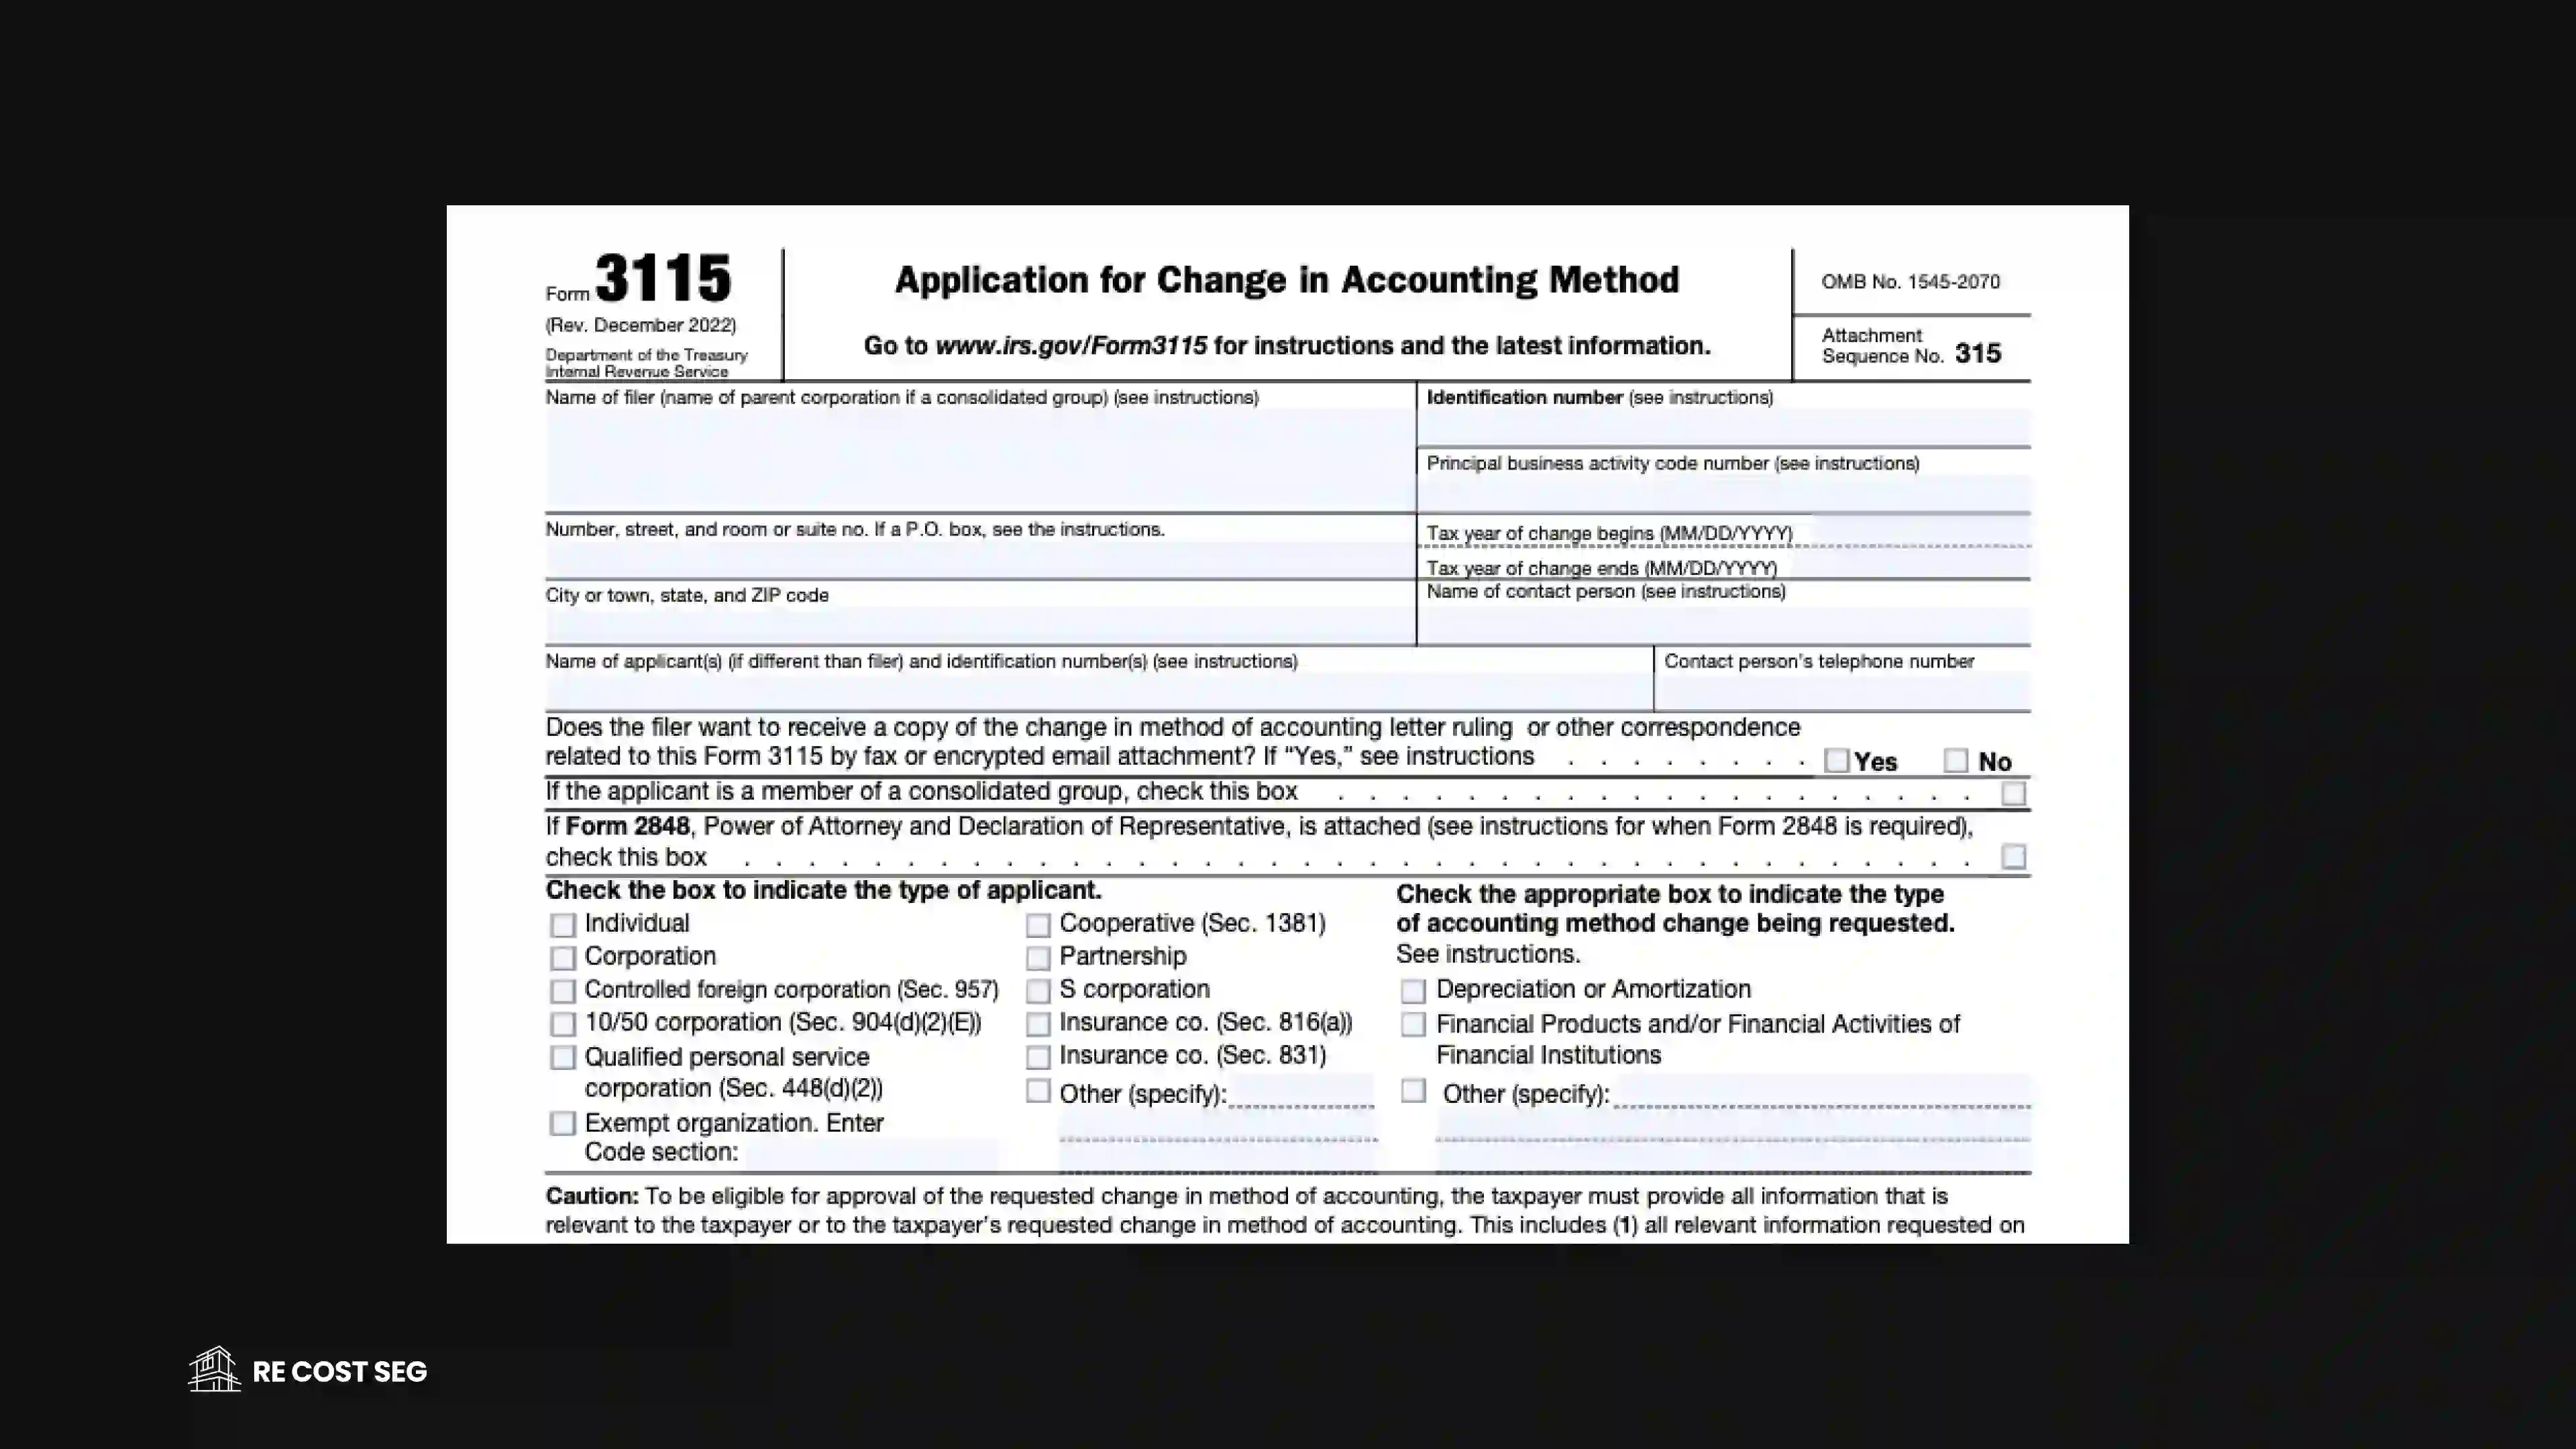

IRS Form 3115, the Application for Change in Accounting Method, is the form taxpayers file to change how they account for an item of income or expense. For real estate investors, it is often how a cost segregation study reaches a property they already depreciate. The missed depreciation is generally captured in one year through a Section 481(a) adjustment, not through years of amended returns.
This matters more now. The One Big Beautiful Bill Act (OBBBA) made 100% bonus depreciation permanent for qualified property acquired after January 19, 2025 (IRS Notice 2026-11). Owners of older properties can still recover depreciation they missed. This guide explains when Form 3115 applies, what the catch-up does and what your CPA decides.
Key Takeaways
- Form 3115 is the IRS application to change an accounting method, including how a property is depreciated.
- A cost segregation study on a property already reported on your returns usually reaches those returns through Form 3115.
- A Section 481(a) adjustment is the cumulative difference between depreciation claimed and depreciation allowable under the corrected method.
- A negative Section 481(a) adjustment is generally taken in full in the year of change, while a positive one is generally spread over four years.
- Whether you file Form 3115 or an amended return depends on how many returns used the old method.
- The catch-up moves deductions you were already entitled to into one year. It does not increase lifetime depreciation.
- Passive activity rules and depreciation recapture can limit or reverse part of the benefit.
What Is IRS Form 3115?
Form 3115 is the IRS form used to request consent to change a method of accounting. Under Treas. Reg. § 1.446-1, certain changes in computing depreciation are treated as accounting method changes. In cost segregation, the change usually moves building components from 27.5- or 39-year real property into 5-, 7- or 15-year classes.
Most of these depreciation changes are automatic changes. A timely, compliant automatic filing needs no user fee and is granted consent, subject to IRS review (Instructions for Form 3115). The current List of Automatic Changes is in Rev. Proc. 2025-23.
Do You Need Form 3115 or an Amended Return?
It depends on how many returns used the old depreciation. Using a depreciation method on two or more consecutively filed returns generally means you adopted it. Changing an adopted method usually requires Form 3115. With only one return filed, an amended return may be available instead.
| Your situation | Usual route | What happens |
|---|---|---|
| Study done before the first return for the property is filed | Original return | Study results are claimed directly. No method change is needed. |
| One return filed with the old classification | Amended return may be available | The single return is corrected. Your CPA confirms eligibility. |
| Two or more consecutive returns filed | Form 3115 with a Section 481(a) adjustment | The catch-up is taken in the year of change. Prior returns stay as filed. |
These are general patterns, not rules for every case. A prior method change for the same item within five tax years can affect automatic-change eligibility. So can an open IRS exam. For the detail, see our guide to the two-return rule.
What Is a Section 481(a) Adjustment?
A Section 481(a) adjustment accounts for the cumulative effect of changing an accounting method, so income and deductions are not counted twice or omitted. In cost segregation, it is generally the difference between depreciation claimed under the old method and depreciation allowable under the corrected method.
The direction of the adjustment sets the timing:
- Negative adjustment (depreciation was under-claimed): generally taken in full in the year of change.
- Positive adjustment (depreciation was over-claimed): generally spread over four tax years, the year of change and the next three.
- Small positive adjustment: an applicant may elect a one-year period if the positive adjustment is less than $50,000.
Most look-back cost segregation studies produce a negative adjustment. Your CPA confirms the amount and its treatment.
How Do You Report Cost Segregation on Your Tax Return?
You report it through the return for the year of change, using the route your CPA selects. At a high level, three things happen:
- The study identifies components that belong in shorter recovery classes.
- Your CPA decides the implementation route based on your filing history.
- Where Form 3115 applies, the method change and the Section 481(a) catch-up are reported with that year's return.
This guide does not cover line-by-line filing. The IRS instructions linked above cover the mechanics, and your CPA should prepare or finalize the form.
How Much Can a Form 3115 Catch-Up Be Worth?
The catch-up equals depreciation you were allowed but did not claim. Older properties with large reclassifications produce the largest one-year deductions. Here is a simplified example.
Assumptions:
- A residential rental is purchased for $750,000 and placed in service in January 2022.
- Land is 20% of the price ($150,000), leaving a $600,000 depreciable basis.
- The owner depreciated the full $600,000 over 27.5 years on the 2022 to 2025 returns.
- A 2026 study reclassifies 25% of the basis ($150,000) into 5-, 7- and 15-year property.
- 2026 is the year of change. The owner is in the 37% federal bracket, can use the loss and has no state tax.
The math:
- Depreciation claimed on the $150,000: 3.485% for 2022 plus 3.636% for each of 2023 to 2025, per the 27.5-year table in IRS Publication 527. That totals about $21,590.
- Depreciation allowable: property placed in service in 2022 qualified for 100% bonus depreciation under the TCJA rules, per Notice 2026-11. Allowable depreciation is $150,000.
- Section 481(a) adjustment: $21,590 claimed minus $150,000 allowable equals a negative adjustment of about $128,410.
- Federal tax value: at 37%, the deduction is worth about $47,512 in 2026.
The trade-off is real. The $150,000 is now fully depreciated, so the $5,454 a year the old schedule produced for it ends. Cost segregation moves deductions earlier. It does not increase total depreciation.
What Can Limit the Benefit?
The deduction is only as useful as your ability to use it. Check these conditions before you count on the savings:
- Passive activity rules: rental losses are generally passive under IRC § 469. Unless an exception applies, such as Real Estate Professional status, the deduction may be suspended.
- Depreciation recapture: when you sell, depreciation on reclassified components can be recaptured and taxed.
- Bonus depreciation rate: the rate depends on the acquisition and placed-in-service dates. Property acquired on or before January 19, 2025 follows the TCJA phase-down.
- Basis reduction: depreciation you were allowed but did not claim still generally reduces your basis for gain purposes.
For cases where a study is not worth it, see when not to do cost segregation.
What Does Form 3115 Include?
Form 3115 identifies the applicant, describes the requested change and reports the Section 481(a) adjustment. For automatic depreciation changes, it also cites the change number from the IRS list. The cost segregation report and depreciation schedules support the change and should be kept with your records.
Common Questions About Form 3115
Can you apply cost segregation to a property you already own?
Yes. A study can be completed years after purchase. If two or more returns used the old classification, the catch-up is generally claimed through Form 3115 and a Section 481(a) adjustment in the year of change. See our guide to look back studies.
Do I need to amend prior returns to claim cost segregation?
Usually not, once the old method has been used on two or more consecutive returns. Form 3115 generally captures the catch-up in the current year instead. With only one return filed, an amended return may be available. Your CPA confirms the route.
Does Form 3115 apply to residential rental properties?
Yes. The method change rules apply to residential rental and commercial property alike. The starting recovery period differs: 27.5 years for residential rental and 39 years for nonresidential real property.
Who calculates the Section 481(a) adjustment?
The calculation is built from the cost segregation study and your depreciation records. A study provider can prepare it, but your CPA should review it against your returns and finalize it.
What happens if I skip Form 3115 when it is needed?
You generally cannot claim the missed prior-year depreciation on your current return. Depreciation you were allowed but did not claim still generally reduces your basis, which can raise your taxable gain at sale.
Final Thoughts on IRS Form 3115
Form 3115 lets investors apply a cost segregation study to a property they already own. The Section 481(a) adjustment brings years of missed depreciation into one tax year. Whether that deduction saves tax now depends on your filing history, passive activity status and exit plans.
Need help implementing your study? R.E. Cost Seg's optional Form 3115 CPA Support Package provides a draft Form 3115, supporting statements and a Section 481(a) calculation. Your CPA reviews and finalizes it. Our standard service does not include signing or filing. Get a free proposal to see what a study could find.
Confirm your situation with your CPA or tax advisor before filing.