
Filing married filing separately changes several important real estate tax rules. The biggest changes hit the passive loss allowance and how you qualify as a Real Estate Professional. Many investors don't learn this until they file, when their CPA delivers unexpected news.
The passive activity loss allowance shrinks or disappears. Real Estate Professional Status (REPS) becomes harder to leverage. Rental property depreciation allocation depends on your state's property laws. And your cost segregation study must be structured to match your filing status from the start.
This article explains the specific complications married filing separately (MFS) creates for depreciation strategy. It walks through community property versus common law state differences. And it shows how to structure your study to capture the deductions your property and filing status support.
Why MFS Changes the Depreciation Equation
Under married filing jointly (MFJ), you can deduct up to $25,000 in passive rental losses against non-passive income. To qualify, you must actively participate in the rental and own at least 10% of it. This allowance phases out between $100,000 and $150,000 of modified adjusted gross income (MAGI), per the IRS Form 8582 instructions.
Under MFS, the rules change based on your living situation, per IRS Publication 925:
- If you lived apart from your spouse for the entire year, the maximum drops to $12,500. It phases out between $50,000 and $75,000 of MAGI.
- If you lived with your spouse at any time during the year, the allowance is zero.
This matters for cost segregation. A study often generates large first-year depreciation deductions. Those deductions can create a rental loss on paper. If the passive activity or at-risk rules prevent you from using the loss against other income, it carries forward instead of producing immediate tax savings.
Even after a Real Estate Professional clears the passive activity rules, the excess business loss limit under Section 461(l) can defer part of the deduction. For 2026, the limit is approximately $512,000 on a joint return but only $256,000 per spouse filing separately. A business loss above the applicable limit is not lost; it becomes a net operating loss carryforward. For example, a sole owner in a common law state who claims the full $280,000 deduction on a separate return could have roughly $24,000 deferred to the next year.
For investors under the $100,000 MAGI threshold, the difference is stark. MFJ allows up to a $25,000 passive loss deduction. MFS allows up to $12,500 if you lived apart all year, and nothing if you lived together.
Can I deduct any rental losses if I file married filing separately?
If you lived apart from your spouse for the entire year, you may use up to the $12,500 special allowance, subject to the $50,000 to $75,000 MAGI phase-out. Beyond that, you generally need to qualify as a Real Estate Professional and materially participate. One nuance helps here: for the material participation test, your spouse's participation still counts, even on a separate return. But for REPS qualification itself, you cannot borrow your spouse's hours. Otherwise, passive losses carry forward until you have passive income to offset or you dispose of the property in a fully taxable transaction.
Community Property States vs. Common Law States
Where you live determines how rental income and depreciation are split between MFS returns. The rules differ between community property states and common law states, as explained in the IRS community property guidance.
Community property states are Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin. In these states, income earned during the marriage is generally community property, owned equally by both spouses. This can apply even when only one spouse holds title to the rental.
There is an important exception. Property acquired before marriage, or received by gift or inheritance, is usually separate property. Separate property is not split 50/50. A valid agreement between spouses can also change the default.
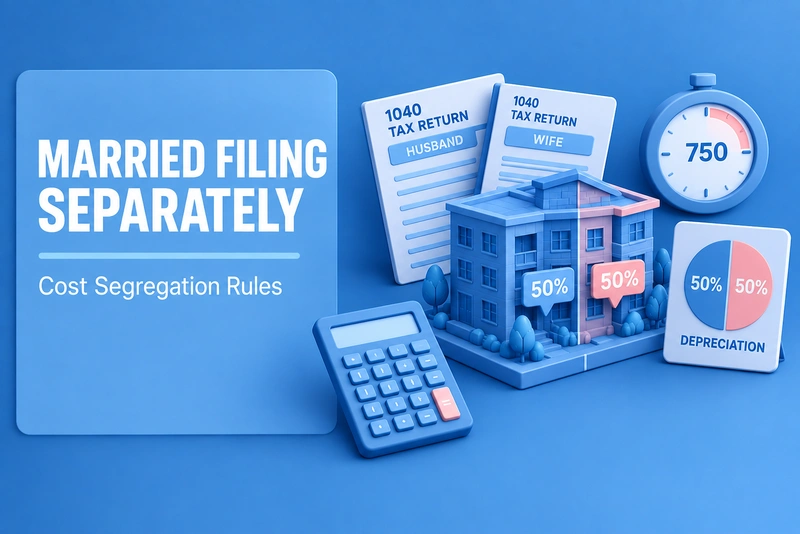
What does this mean for depreciation? For community property, each spouse reports 50% of the rental income and claims 50% of the depreciation on their separate return.
Here is a Texas example. One spouse owns a $1 million rental property held as community property. A cost segregation study reclassifies $280,000 into 5-, 7-, and 15-year property. With 100% bonus depreciation, permanently restored by the One Big Beautiful Bill Act for property acquired and placed in service after January 19, 2025, per IRS guidance, the first-year accelerated deduction is $280,000. Under MFS in Texas, each spouse reports $140,000 of that deduction. Each spouse also reports 50% of the rental income.
Here is a Florida example. Same scenario, one spouse owns a $1 million rental. Florida is a common law state by default, so income and deductions follow ownership. Under MFS, only the owning spouse reports the rental income and claims the full $280,000 deduction. The non-owning spouse reports nothing from that property. Note that Florida also lets couples opt into community property through a trust, which would change this result.
The distinction affects tax bracket planning, passive loss use, and overall strategy. Your CPA must account for your state's property laws when integrating a cost segregation study into MFS returns.
Real Estate Professional Status Under MFS
Real Estate Professional Status removes the passive activity limits on rental depreciation for activities in which you materially participate. Under MFJ, one qualifying spouse can benefit the joint return. Under MFS, each spouse stands alone.
To qualify, an individual must perform more than 750 hours of service in real property trades or businesses during the year. More than half of that person's total personal services must also be in real property trades or businesses, per IRC Section 469(c)(7). Hours are never combined between spouses, one individual must clear both thresholds on their own. On a joint return, that one qualifying spouse is enough; on separate returns, the qualification helps only that spouse's own return.
This creates a strategic decision. If only one spouse qualifies as a Real Estate Professional, filing MFJ lets that qualification benefit all rental properties on the joint return. Filing MFS means only the qualifying spouse's return benefits. And it helps only for properties in which that spouse materially participates.
For investors who rely on REPS to offset W-2 income with cost segregation deductions, this can mean the difference between a six-figure refund and a carried-forward loss.
Does my spouse's Real Estate Professional Status help me if we file separately?
Not for REPS qualification. Under MFS, each spouse's REPS status applies only to their own return. If your spouse qualifies but you do not, your rental losses stay subject to passive activity limits on your separate return. This is one of the strongest arguments for filing MFJ when one spouse is a Real Estate Professional.
Structuring Your Cost Segregation Study for MFS
The ownership structure of your property determines how depreciation is allocated on MFS returns.
Sole ownership. If one spouse holds title individually, that spouse claims 100% of the depreciation in common law states, or 50% in community property states.
Joint tenancy. Both spouses own equal shares. Each claims 50% of the depreciation on their separate return.
Tenancy in common. Each spouse owns a specified percentage. Depreciation follows the ownership split.
Here is how this works. A couple owns a $750,000 rental property as tenants in common, split 60/40. After an 18% land value exclusion, the depreciable basis is $615,000. A study reclassifies 30%, or $184,500, into 5-, 7-, and 15-year property. With bonus depreciation, the full $184,500 is deductible in year one. Under MFS, Spouse A claims $110,700 (60%) and Spouse B claims $73,800 (40%).
Form 3115 considerations. A look-back study uses Form 3115 to claim catch-up depreciation as a change in accounting method. Under MFS, each spouse generally reports their own share on their own return. Confirm the exact mechanics with your CPA. Your cost segregation firm should deliver split schedules that match each spouse's ownership percentage and filing status.
Coordination with your CPA is essential. The study must align with your filing status from the start, not be retrofitted after the fact.
When MFS Makes Sense Despite the Limitations
MFS is rarely the default choice. But specific situations make it the right one.
Income-driven student loan repayment. MFS can keep each spouse's income separate for federal student loan repayment calculations. The tax cost of a smaller passive loss allowance may be worth the savings on monthly loan payments.
Spouse liability protection. If one spouse has outstanding tax debts, IRS liens, or compliance issues, MFS can protect the other spouse from joint liability.
AGI-sensitive deductions. In a common law state, a spouse with large medical or casualty deductions may clear the AGI floor on a separate return when they would not on a joint one. Run both filings; MFS wins less often than people expect.
Even with MFS limits, cost segregation still generates value. Accelerated depreciation reduces taxable rental income. It also lowers your adjusted basis, which increases depreciation recapture exposure at a future sale. And it creates carried-forward losses that can offset passive income in later years.
Plan Before You File
MFS adds complexity to your depreciation strategy. It does not eliminate the benefits.
- Three limits can restrict a cost segregation loss: the passive activity rules, the at-risk rules, and the excess business loss limit. Under MFS, the special passive loss allowance drops to $12,500 if you lived apart all year and to zero if you lived together at any point; the excess business loss limit is also half the joint-return amount. Plan for carried-forward losses or pursue REPS qualification independently.
- Your state matters. Community property states split income and depreciation 50/50 for community property. Common law states follow ownership.
- Coordinate early. Your cost segregation firm and CPA must align the study with your filing status before the return is prepared.
Get a free proposal and map out the filing strategy that fits your property with your CPA. The right structure captures the deductions your property supports.